In short
- Stair lift chair and platform with no cover and no shaft: 6% VAT (CIVA item 2.9, item 39 of Despacho 26026/2006).
- Lifts with a cabin or shaft: 23% VAT on the mainland, according to the AT.
- In IRS we found no deduction of its own; articles 78-C and 87 are possible, but the AT has not confirmed them for this equipment.
- Article 87 requires 60% incapacity or more, proved by a multi-purpose certificate.
Anyone buying a stair lift or a platform asks what VAT they pay and whether income tax (IRS) gives anything back. This guide shows what the law and the tax authority (AT) write, and what you still need to confirm before you sign a quote.
Updated on 3 November 2026. General information; it does not replace the opinion of the tax office or of a certified accountant.
The essentials
- Stair lift chair and platform with no cover and no shaft: 6% VAT. Item 2.9 of List I of the VAT Code (CIVA) applies the reduced rate to devices for people with a disability that appear on an official list. The list includes “elevators to fit on stairs”.
- Home lift with a cabin or shaft: 23% VAT on the mainland, according to the AT (binding information 14219, 2018).
- In IRS we found no deduction of its own for buying a stair lift. There are two possible doors, health expenses (article 78-C of the IRS Code) and rehabilitation of people with a disability (article 87), but we read no AT text that confirms them for this equipment.
- The 60% threshold. Article 87 requires a degree of incapacity of 60% or more, proved by a Multi-purpose Medical Incapacity Certificate (AMIM). For the 6% VAT rate, the AT texts we read do not ask the buyer for that certificate.
- Ask in writing for the rate and the item on the invoice, with equipment and labour listed separately.
VAT: what item 2.9 says
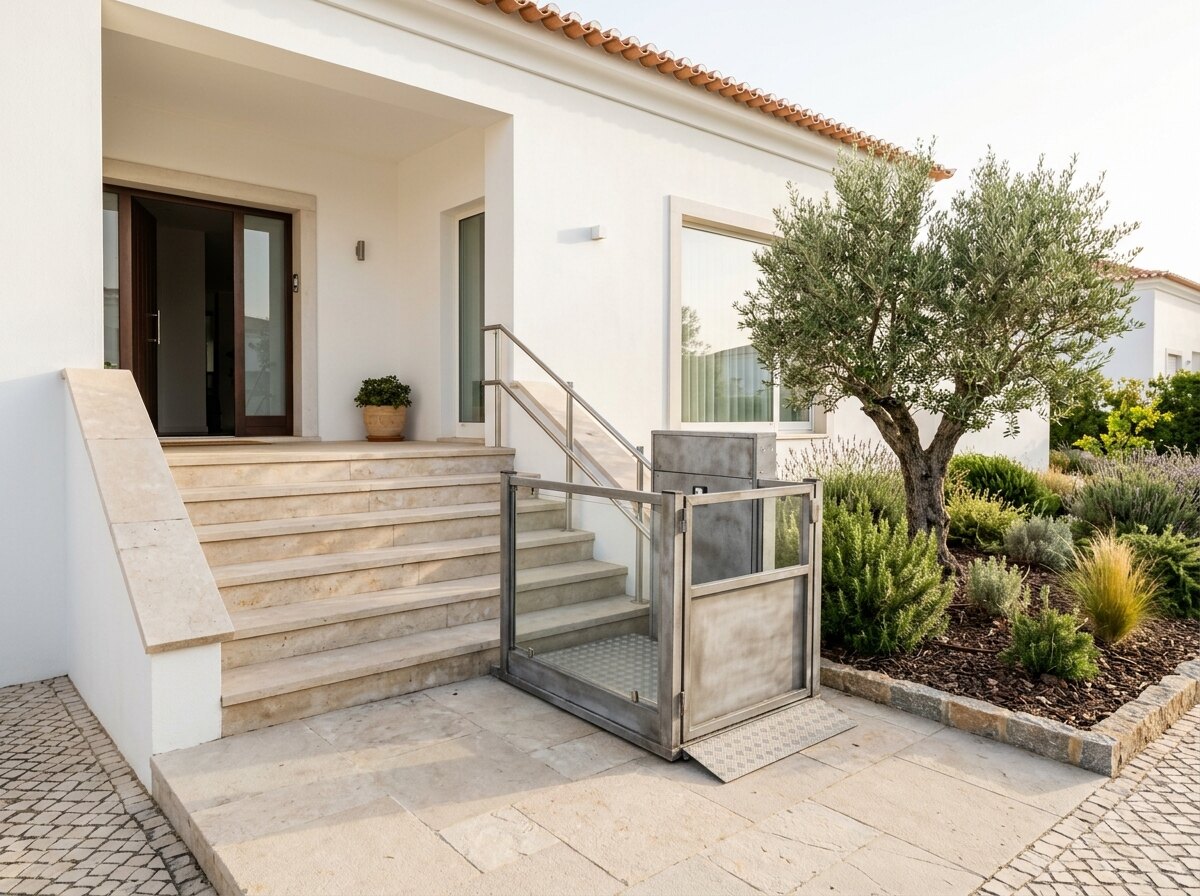
The reduced rate is 6% (the AT writes “currently 6%” in information 27150, December 2024; the texts speak of the mainland). Item 2.9 of List I covers “utensils and any devices or objects specifically designed for use by people with a disability, provided they appear on a list approved by joint order”. That list is Joint Order (Despacho Conjunto) no. 26026/2006 of 22 December. Its item 39 mentions “lifting platforms and wheelchair lifts (with no cover, not working inside a shaft)”, “elevators to fit on stairs” (with a seat or platform fixed to one or more rails that follow the staircase), “stair climbers” and portable ramps.
The AT applied this item in 2018 (informations 14024 and 14219) and again in August 2025 (information 28824, on swimming-pool lifts).
When VAT is 23%
- Platform with a cover. In information 14024 only the model with no cover and no shaft got 6%. Those with a top cover stayed at 23%.
- Equipment with a cabin or enclosing structure. In information 14219, pneumatic lifts with a cabin, even with no shaft, fell outside item 2.9. The AT concluded that the CIVA has no exemption for lifting equipment and that the normal rate applies “regardless of the nature of the buyer”. See the guide on the home lift.
And the installation?
Both AT texts deal with the “supply” of the equipment. We found no AT text saying how installation labour is taxed when it is on the same invoice. There are two clues, which do not replace the supplier’s answer:
- Item 2.27 gives 6% to works of improvement, repair or maintenance of buildings used as housing. But Circular Letter 30135 (26 September 2012) says that supplying lifts stays at the normal rate and that, when materials exceed 20% of the value of the job, only labour gets 6%, and only if the invoice lists it separately.
- Item 2.30 gives 6% to maintenance and repair of the goods in items 2.6, 2.8 and 2.9. It serves for future servicing.
For works around the equipment, see the guide on comparing quotes. In an urban rehabilitation area, the AT accepted 6% (item 2.23) for replacing a building’s lift under a works contract (information 27150). We found no decision on stair lift chairs.
IRS: what exists
Article texts as shown on the Portal das Finanças on 3 November 2026. For article 78-C, the latest amendment is Decree-Law 49/2025.
Health expenses (article 78-C of the IRS Code). Deduction of 15% of the expense, up to 1,000 euros for the whole household. The invoice must carry VAT exempt or at 6%, and the issuer must work in health activities (class 86, or CAE 47730, 47740 and 47782). Invoices at 23% count only with a medical prescription. The article does not mention equipment for people with a disability, and we found no AT answer on stair lifts.
Rehabilitation (article 87, no. 2). Deduction of 30% of education and rehabilitation expenses of a person with a disability (or of dependants), not exceeding 15% of the IRS due (no. 4). In a 2024 information (process 24802), the AT said only services from licensed bodies and “assistive products” from lists approved under Decree-Law 93/2009 count. It refused the repair of the building’s lift. The list in force, INR Despacho 11077/2025, has codes 18 30 10 (stair lifts with seat) and 18 30 11 (with platform). This suggests a stair lift may count, but the AT did not write it. Before relying on it, ask for a binding information.
In the Tax Benefits Statute (EBF) we found no article on this purchase. Article 78-E of the IRS Code (housing costs) speaks only of rents and interest.
The certificate and the 60%
Article 87, no. 5, requires permanent incapacity of 60% or more, proved by an AMIM. You ask for it at the health centre, on the Gov.pt portal or on SNS 24. You then must report the situation to the tax office (Portal das Finanças, “Situação de Incapacidade”). If the degree drops after a re-assessment, see no. 9 and the AT leaflet of July 2026.
Questions for the supplier and the tax office
- What is the model, does it have a cover, cabin or shaft, and which item of Despacho 26026/2006 does it fall under?
- Does the invoice state the rate and the item, and separate equipment, installation and works?
- Does the invoice carry my tax number (NIF) and the issuer’s CAE?
- May I ask for a binding information (article 68 of the General Tax Law) on the IRS deduction?
To choose the equipment for your staircase, use the selection tool. For direct support, see who pays.
What we could not confirm
- There is no AT binding information on a stair lift chair on stairs. Those we read concern platforms and lifts, but they cite item 39.
- We do not know how the AT taxes installation sold with the equipment.
- We did not confirm whether the buyer must prove the disability to get 6%. The texts we read do not ask for it.
- We do not know whether a child paying for a parent can deduct under article 87.
- The Northern Central Administrative Court judged in 2023 (case 01494/13.0BEPRT) whether “residential lifts” fall under item 2.9; we read only the report, not the decision. The text of the order was read in the copy on the AT page, not in the Diário da República.
Sources (read on 3 November 2026)
- Portal das Finanças, CIVA List I, items 2.6, 2.9, 2.23, 2.27, 2.30 and Joint Order 26026/2006: https://info.portaldasfinancas.gov.pt/pt/informacao_fiscal/codigos_tributarios/civa_rep/Pages/c-iva-listas.aspx
- AT, VAT binding informations 14024 (2018), 14219 (2018), 27150 (2024), 28824 (2025), at info.portaldasfinancas.gov.pt.
- AT, Circular Letter 30135, 26/9/2012 (item 2.27), under administrative instructions.
- IRS Code, articles 78-C, 78-E and 87, on the Portal das Finanças.
- AT, IRS binding information 24802 (26/8/2024).
- INR, Despacho 11077/2025 of 19/9/2025, Annex I (codes 18 30): https://files.diariodarepublica.pt/2s/2025/09/181000000/0008700121.pdf
- AT, leaflet “People with a tax-relevant disability” (July 2026).
- TCA Norte, judgment 01494/13.0BEPRT, cited through vLex, not read in full.
Questions and answers
6%, under item 2.9 of CIVA List I, because item 39 of Despacho 26026/2006 includes elevators to fit on stairs. Source: Portal das Finanças and binding information 14024.
When the equipment has a cover, cabin or enclosing structure, or works in a shaft. The AT applied the normal rate to these cases in informations 14024 and 14219.
We found no deduction of its own and no AT answer. Articles 78-C (health, 15%) and 87 (rehabilitation, 30%) are possible, but ask for a binding information.
For the article 87 deduction yes (Multi-purpose Medical Incapacity Certificate). For 6% VAT the AT texts we read do not ask the buyer for it.